A Bal Harbour condo budget is about more than the purchase price. Monthly association fees, insurance, reserves, assessments, financing terms, and closing costs can all influence the true cost of ownership. Knowing which documents and numbers to review early helps buyers compare residences with greater clarity and fewer surprises.
Start With the Complete Monthly Picture
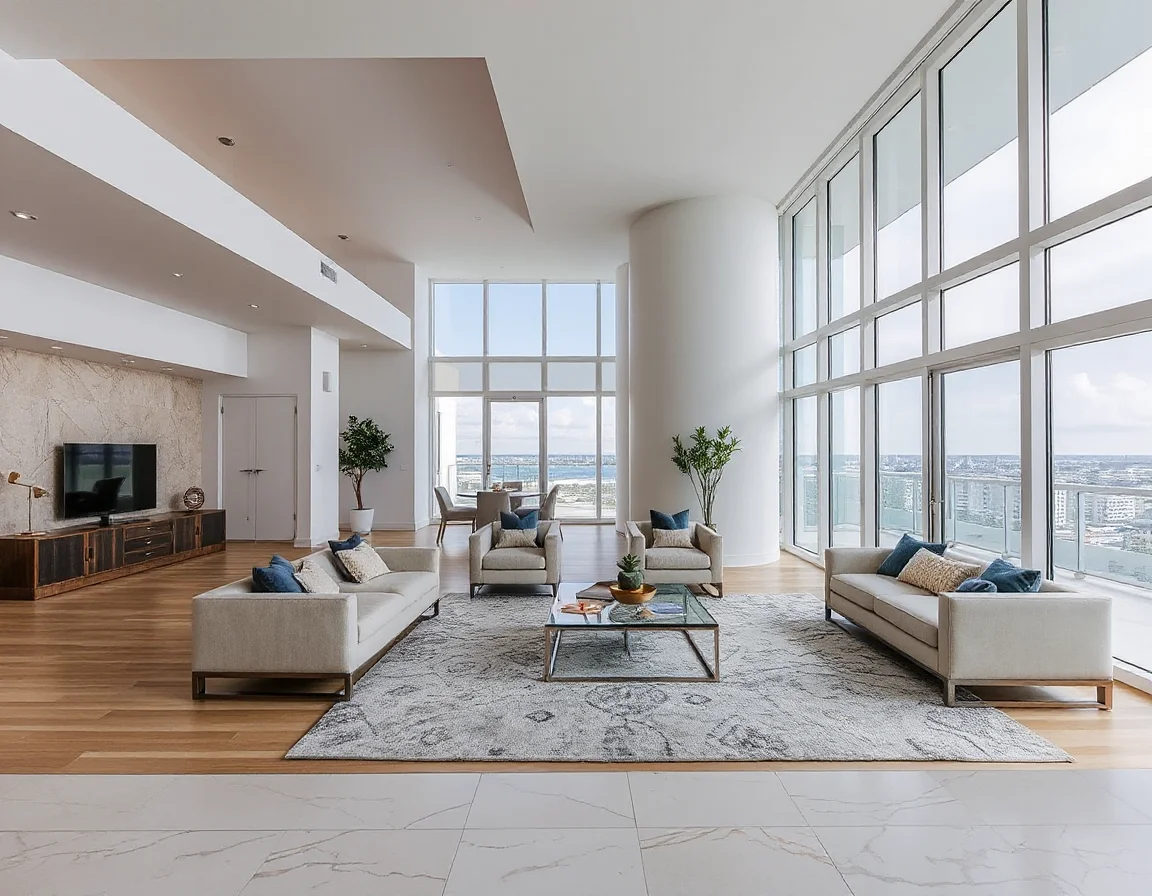
Bal Harbour offers a distinctive mix of oceanfront towers, bay-facing residences, and established condominium communities along Florida’s coastline. The setting can make it easy to focus on a residence’s views, finishes, and location, but a confident purchase begins with a complete operating budget. Before narrowing a search, it helps to separate one-time acquisition costs from the recurring expenses that continue after closing.
The purchase price establishes the starting point, but the monthly payment may include principal and interest, property taxes, homeowners insurance, association dues, parking or storage fees, and utility charges not covered by the building. For cash purchases, there may be no mortgage payment, yet dues, taxes, insurance, and maintenance still deserve the same careful attention. Comparing residences based on the total monthly and annual outlay creates a more useful picture than comparing asking prices alone.
Association dues vary widely because each building has its own amenities, staffing levels, maintenance plans, utility arrangements, insurance policies, and reserve funding. A building with attended entry, valet service, elevators, pools, fitness facilities, landscaping, and beachfront operations may carry a different fee structure than a smaller property with fewer shared features. Higher dues are not automatically a negative; the key question is what the fee covers and whether the budget appears sustainable.
Ask for the current association budget, fee schedule, reserve information, and the most recent meeting minutes before making assumptions from a listing’s monthly dues figure.
For a practical comparison, create a simple worksheet for each property. List the advertised price, estimated loan payment if applicable, association fee, tax estimate, insurance estimate, expected utility cost, and any known recurring charges. Then add a line for a contingency reserve for routine interior maintenance. This approach makes it easier to identify which residences fit your preferred ownership budget rather than simply your preferred purchase price.
Understand What Condo Association Fees Cover
Condominium dues are often the cost category buyers want to understand most clearly, and for good reason. In a shared building, the association is responsible for maintaining common elements and coordinating many services that would be handled individually in a detached home. Depending on the property, fees may include building insurance, water, sewer, trash collection, exterior upkeep, landscaping, pest services, security-related staffing, management, cable or internet packages, and amenity maintenance.
Coverage differs from building to building, so request an itemized explanation rather than relying on broad descriptions. For example, one residence may include air-conditioning maintenance, while another may assign that responsibility to each owner. Some buildings include certain utilities in the monthly fee; others bill them separately. The answers can change the effective monthly cost and should be considered alongside the amenities and condition of the property.
It is also useful to review the association’s financial statements with care. Look at operating income and expenses, reserve balances, current projects, outstanding loans if any, and the pattern of prior fee increases. Meeting minutes can provide context about upcoming repairs, vendor changes, insurance discussions, or capital improvements. A qualified real estate professional, attorney, lender, and financial adviser can each help buyers interpret the materials relevant to their role.
A low monthly fee can be appealing, but it should be evaluated in context. If a building has major maintenance needs and limited reserves, the association may need to increase dues or levy an assessment in the future. Conversely, a higher fee may reflect services, reserves, or operating costs that are clearly identified in the budget. The goal is not to find one “right” number; it is to understand the financial framework behind the number.
Plan for Taxes, Insurance, and Financing
Property taxes are another major part of condo ownership costs. Tax amounts can change after a sale because assessed values, exemptions, and local tax rates may differ from the prior owner’s situation. A listing’s historical tax figure is helpful background, but it should not be treated as a guaranteed future bill. Buyers can ask their real estate and tax professionals how to estimate taxes for the anticipated purchase price and ownership structure.
Insurance deserves equal attention in coastal South Florida. The association typically insures portions of the building and common elements, while an individual owner may need a separate policy for the interior of the unit, personal property, liability, deductibles, and other exposures described in the condominium documents. Lenders may also set coverage requirements. Requesting insurance quotes early gives buyers time to understand available options and include them in their projections.
Financing can add another layer of review. Loan programs, down-payment requirements, interest rates, reserve standards, and building eligibility can all vary. Some lenders review the condominium project as well as the individual borrower, which means association documentation can affect both the approval timeline and available financing choices. A pre-approval from a lender experienced with condominium transactions is a useful starting point, but buyers should also confirm the lender’s requirements for the specific property under consideration.
In addition to the loan itself, remember that the monthly figure may include escrowed taxes and insurance. A loan estimate will outline projected payments and closing charges, allowing buyers to compare financing scenarios consistently. It is wise to leave room for rate changes, renewal premiums, and ordinary increases in operating expenses rather than budgeting only to today’s estimate.
In a condo purchase, the building’s documents matter almost as much as the residence itself. Review deadlines for association materials early so there is time to ask focused questions.
Prepare for Closing Costs and Future Projects
Closing costs are the one-time expenses required to complete a purchase. Depending on the transaction, these may include lender charges, appraisal and inspection costs, title and settlement services, government recording fees, prepaid items, escrow deposits, attorney fees, and association application or transfer charges. Cash buyers may avoid lender-related charges, but still have title, inspection, association, and settlement expenses to plan for.
Association approval procedures can have their own timeline and fees. Buyers should ask about application forms, processing charges, interview requirements where applicable, move-in deposits, elevator reservations, vehicle registration procedures, and rules governing renovations or deliveries. These are not merely administrative details: they can influence the timing and cost of moving into the residence after closing.
Special assessments are another item to explore. An assessment may be used to fund a large repair, insurance expense, infrastructure upgrade, or other project beyond regular operating costs. Ask whether there are current assessments, proposed projects, or recently completed work, and review the terms for any payment plan. Understanding these details before making an offer supports a more complete financial decision.
For buyers considering updates after purchase, include renovation planning in the budget as well. Buildings may require deposits, insurance certificates from contractors, architectural review, work-hour restrictions, and permits. A detailed plan can help align the desired improvements with the building’s policies and the available budget.
Use Due Diligence to Make a Clearer Decision
The most effective way to navigate Bal Harbour condo costs is to ask precise questions early and keep every estimate in one place. Review the listing details, association records, insurance information, tax estimates, financing terms, and closing disclosures with the appropriate professionals. If a cost is uncertain, label it as an estimate and build in a reasonable cushion rather than overlooking it.
With a complete picture, buyers can spend less time reacting to individual line items and more time evaluating how a particular residence supports their priorities. Whether the appeal is an ocean outlook, a bay setting, building amenities, or proximity to local destinations, a well-organized cost review helps turn a compelling property search into a well-informed ownership decision.